A manufactured home can make homeownership feel more attainable without asking you to compromise on comfort, space, or community. But protecting that investment calls for coverage designed for the way manufactured homes are built, installed, and lived in. This manufactured home insurance guide explains what a policy may cover, where gaps can appear, and how to choose coverage that supports your household and your budget.
Insurance is not just paperwork for a lender or community requirement. It is a practical plan for getting back on your feet after a covered loss, whether that means storm damage, a kitchen fire, theft, or an accident that affects someone visiting your home.
What Manufactured Home Insurance Usually Covers
Manufactured home insurance is similar to a standard homeowners policy in several ways, but it is written specifically for factory-built homes. Policies and state requirements vary, so the declarations page and endorsements matter more than a policy name alone.
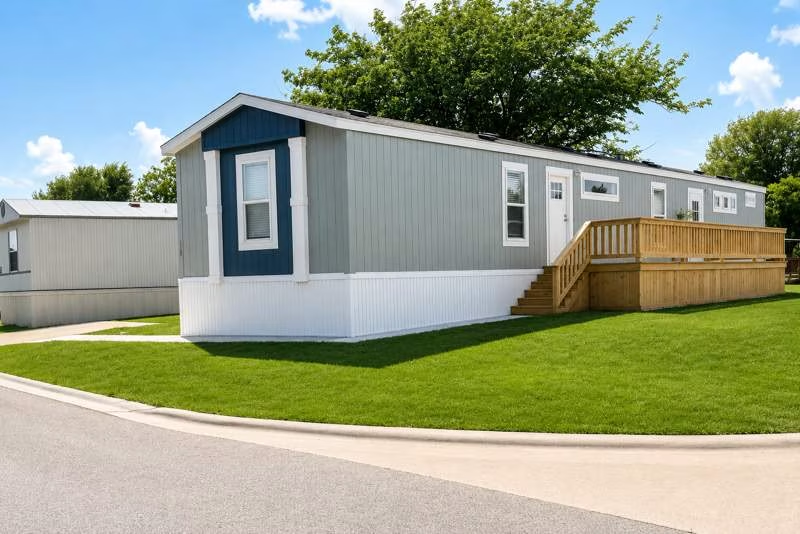
The central part of the policy is usually dwelling coverage. This helps pay to repair or replace the home after a covered event, subject to the policy limit, deductible, and terms. Depending on the insurer and policy, attached structures such as a porch, deck, awning, or carport may be included in the dwelling limit or covered separately.
Personal property coverage helps protect the things that make a home yours: furniture, clothing, appliances, electronics, cookware, and other belongings. Many people set this limit once and never revisit it. That can leave them underinsured after adding a new television, replacing furniture, setting up a home office, or simply accumulating everyday household items over time.
Most policies also include personal liability coverage. If a guest is injured at your home or you accidentally damage another person’s property, liability coverage may help with covered legal and settlement costs. A related benefit, often called medical payments coverage, may help with smaller guest injury claims regardless of fault, up to the stated limit.
Finally, ask about loss of use coverage. If a covered claim makes your home temporarily unlivable, this coverage can help with additional living expenses such as a hotel, short-term rental, meals, or other necessary costs above your normal household spending. The exact limits and qualifying expenses differ by carrier.
The Events a Policy May Cover
Many manufactured home policies cover certain sudden and accidental events, commonly including fire, lightning, wind, hail, smoke damage, vandalism, theft, and damage from certain falling objects. Water damage from a burst pipe may also be covered, while gradual leaks, poor maintenance, and flooding often are not.
The word “covered” does a lot of work here. A policy can protect against wind damage but apply a separate wind or hurricane deductible. It may cover water damage from an accidental appliance leak but exclude damage caused by repeated seepage. It may cover the home itself while limiting payment for valuable jewelry, firearms, collectibles, or business equipment.
That is why the best question is not simply, “Does this policy cover storms?” Ask, “What storm damage is covered, what deductible applies, and what exclusions should I plan for?” Clear answers now are far easier than surprises during a claim.
Replacement Cost vs. Actual Cash Value
One of the biggest choices in any manufactured home insurance guide is how claims are valued.
Replacement cost coverage generally pays the cost to repair or replace covered property with materials of similar kind and quality, without deducting for depreciation, up to policy limits and subject to policy conditions. It often costs more, but it can provide stronger protection when rebuilding prices rise.
Actual cash value coverage factors in depreciation. If an older roof, appliance, or piece of furniture is damaged, the payment may reflect its age and condition rather than what it costs to buy a new replacement. The lower premium can be appealing, especially for a tight monthly budget, but the out-of-pocket difference after a claim can be significant.
Neither option is automatically right for every household. Consider your savings, the age and condition of your home, your loan requirements, and how much financial risk you are prepared to carry after a loss.
Coverage Gaps Homeowners Should Plan For
Some of the most expensive risks require separate coverage or added endorsements. Flood damage is the clearest example. Standard manufactured home policies typically do not cover flooding caused by overflowing waterways, storm surge, or heavy rain accumulating on the ground. Even homes outside a high-risk flood zone can face localized flooding, so it is worth reviewing your property’s exposure.
Earthquake coverage is also commonly excluded or limited. Residents in areas where seismic risk is a concern should ask whether a separate policy or endorsement is available. In parts of the country with severe wind, hail, tornadoes, or hurricanes, review whether special deductibles apply and how the home must be anchored or maintained for coverage to remain in place.
Utility line failures, water backup through sewers or drains, identity theft, and equipment breakdown are other items that may be available as optional coverage. These additions are not necessary for everyone. They are worth considering when the cost of the added protection is reasonable compared with the disruption and expense the event could create.
How Much Coverage Is Enough?
Do not base dwelling coverage only on the price you paid for the home. Market value, loan balance, and rebuild cost are different numbers. The amount needed to replace a home after a serious loss may be affected by labor costs, material prices, local building requirements, transport, installation, debris removal, and the cost of bringing systems up to current code.
Start with the insurer’s replacement-cost estimate, then ask what assumptions it uses. Make sure the home’s size, year, features, roof type, additions, and improvements are accurately listed. A remodeled kitchen, new flooring, expanded deck, or upgraded HVAC system can change the value that needs protection.
For personal property, walk through each room with your phone and create a simple inventory. Take photos or video, note model numbers for larger items, and save receipts for major purchases when possible. Store the inventory somewhere accessible outside the home, such as secure cloud storage. It can make the claim process more organized during an already stressful time.
Choosing a Deductible That Fits Your Budget
Your deductible is the amount you pay before insurance begins paying on a covered claim. A higher deductible generally lowers the premium. A lower deductible can reduce your immediate financial burden after a loss, but it usually raises the yearly or monthly cost.
Choose a deductible you could realistically cover without relying on high-interest debt. If you select a $2,500 deductible to reduce your premium, keep a plan for where that $2,500 would come from after a covered event. For wind or hurricane claims, confirm whether a separate percentage deductible applies. A percentage sounds small until it is calculated against the insured value of the home.
Questions to Ask Before You Buy or Renew
A helpful agent or insurer should be willing to explain the policy in plain language. Before committing, ask whether the policy is replacement cost or actual cash value, how the home is valued, and whether attached structures are included. Confirm the deductibles for standard claims and weather-related claims, as well as the limits for personal property, liability, and additional living expenses.
Also ask whether your home’s installation, tie-downs, skirting, roof condition, and occupancy status affect eligibility. If you rent out the home, use part of it for business, leave it vacant for extended periods, or own high-value items, standard coverage may not be enough.
Price matters, especially for households focused on predictable costs. Still, the least expensive quote is not always the best value. Compare similar coverage limits, deductibles, exclusions, and claim settlement methods before deciding. A lower premium can be worthwhile, but only if you understand what you are giving up.
Keep Your Policy Current as Your Home Changes
Insurance should be reviewed at least once a year and after any meaningful change. Notify your insurer when you complete renovations, add a porch or shed, purchase expensive belongings, install a security system, or change how the home is occupied. Ask about discounts for protective devices, bundled policies, claims-free history, or newer roofs, but make coverage decisions based on protection first and savings second.
Well-maintained homes and attentive communities both support peace of mind, but they do not replace insurance. Regularly checking your policy gives you a clearer path forward when life takes an unexpected turn – and lets you keep enjoying the home and community you have worked hard to build.